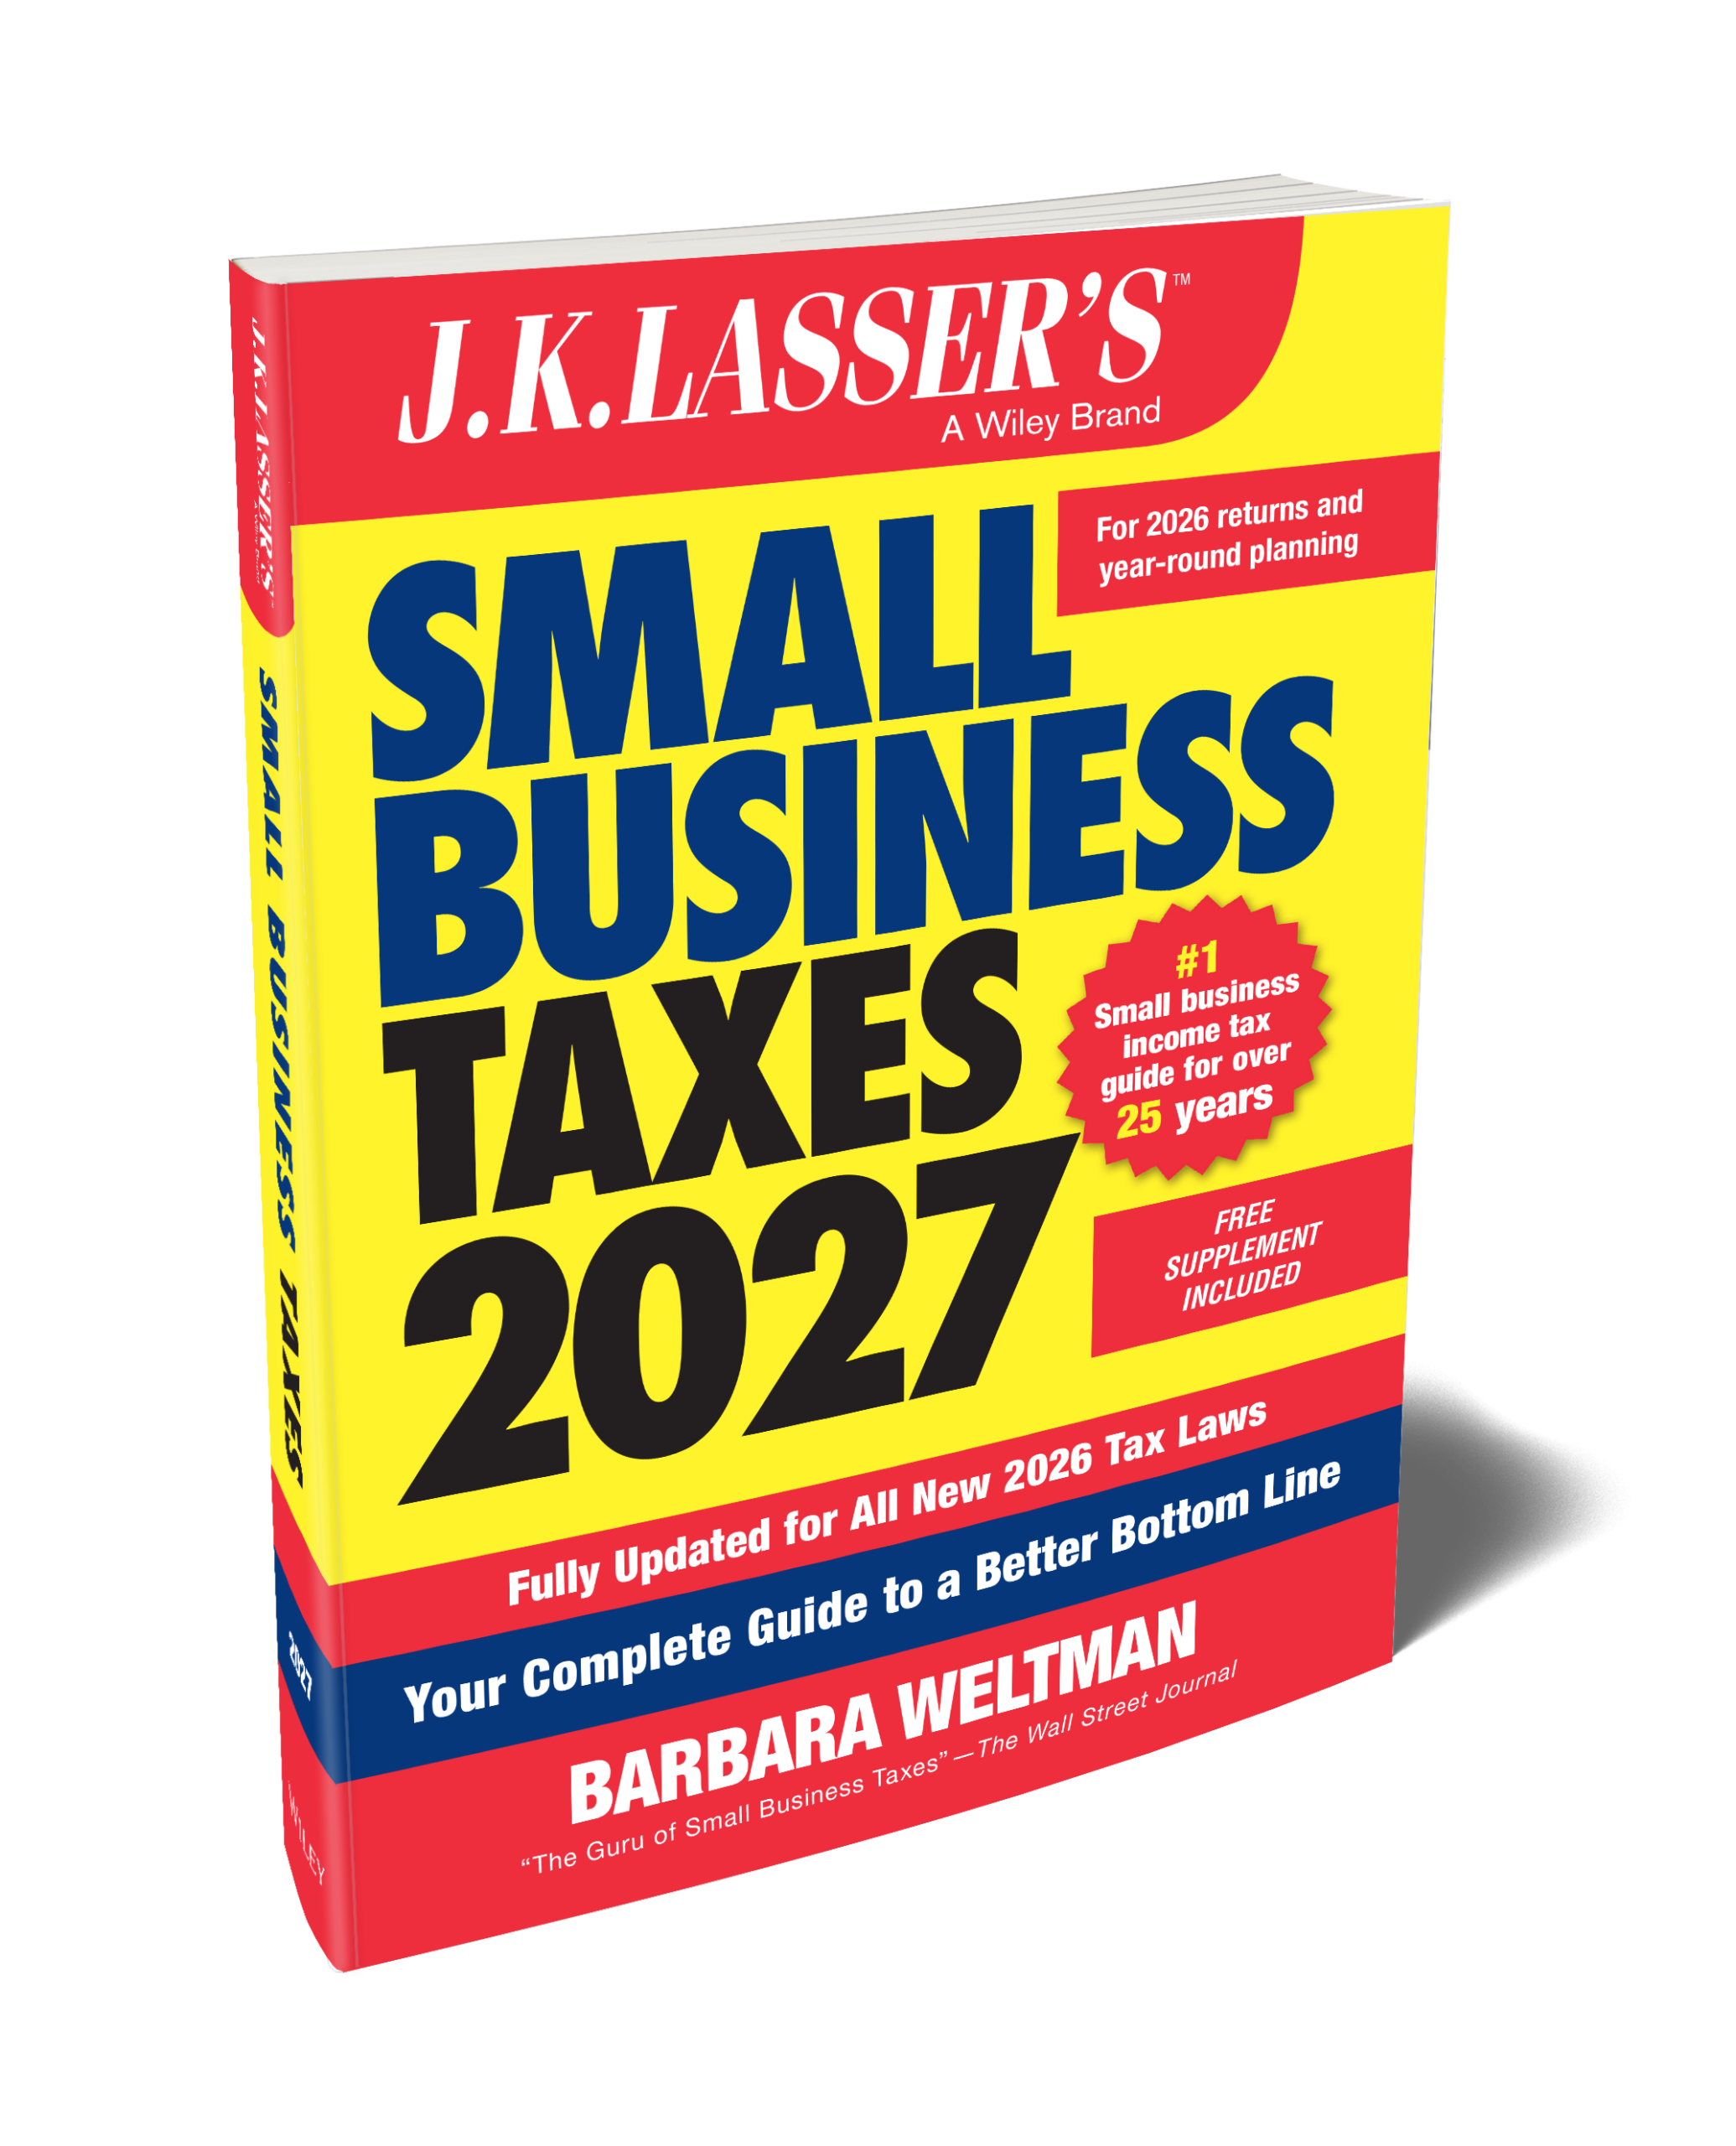
$25.00 
Learn more
A minister may be eligible for the qualified business income (QBI) deduction if he or she performs weddings, funerals, or other activities the income from which is reported on Schedule C. Wages received from an employer do not qualify for the QBI deduction.
The length of time that an asset is owned and that generally determines long- or short-term capital gain treatment.
Copyright © 2000- John Wiley & Sons, Inc., or related companies. All rights reserved. Please read our Privacy Policy.