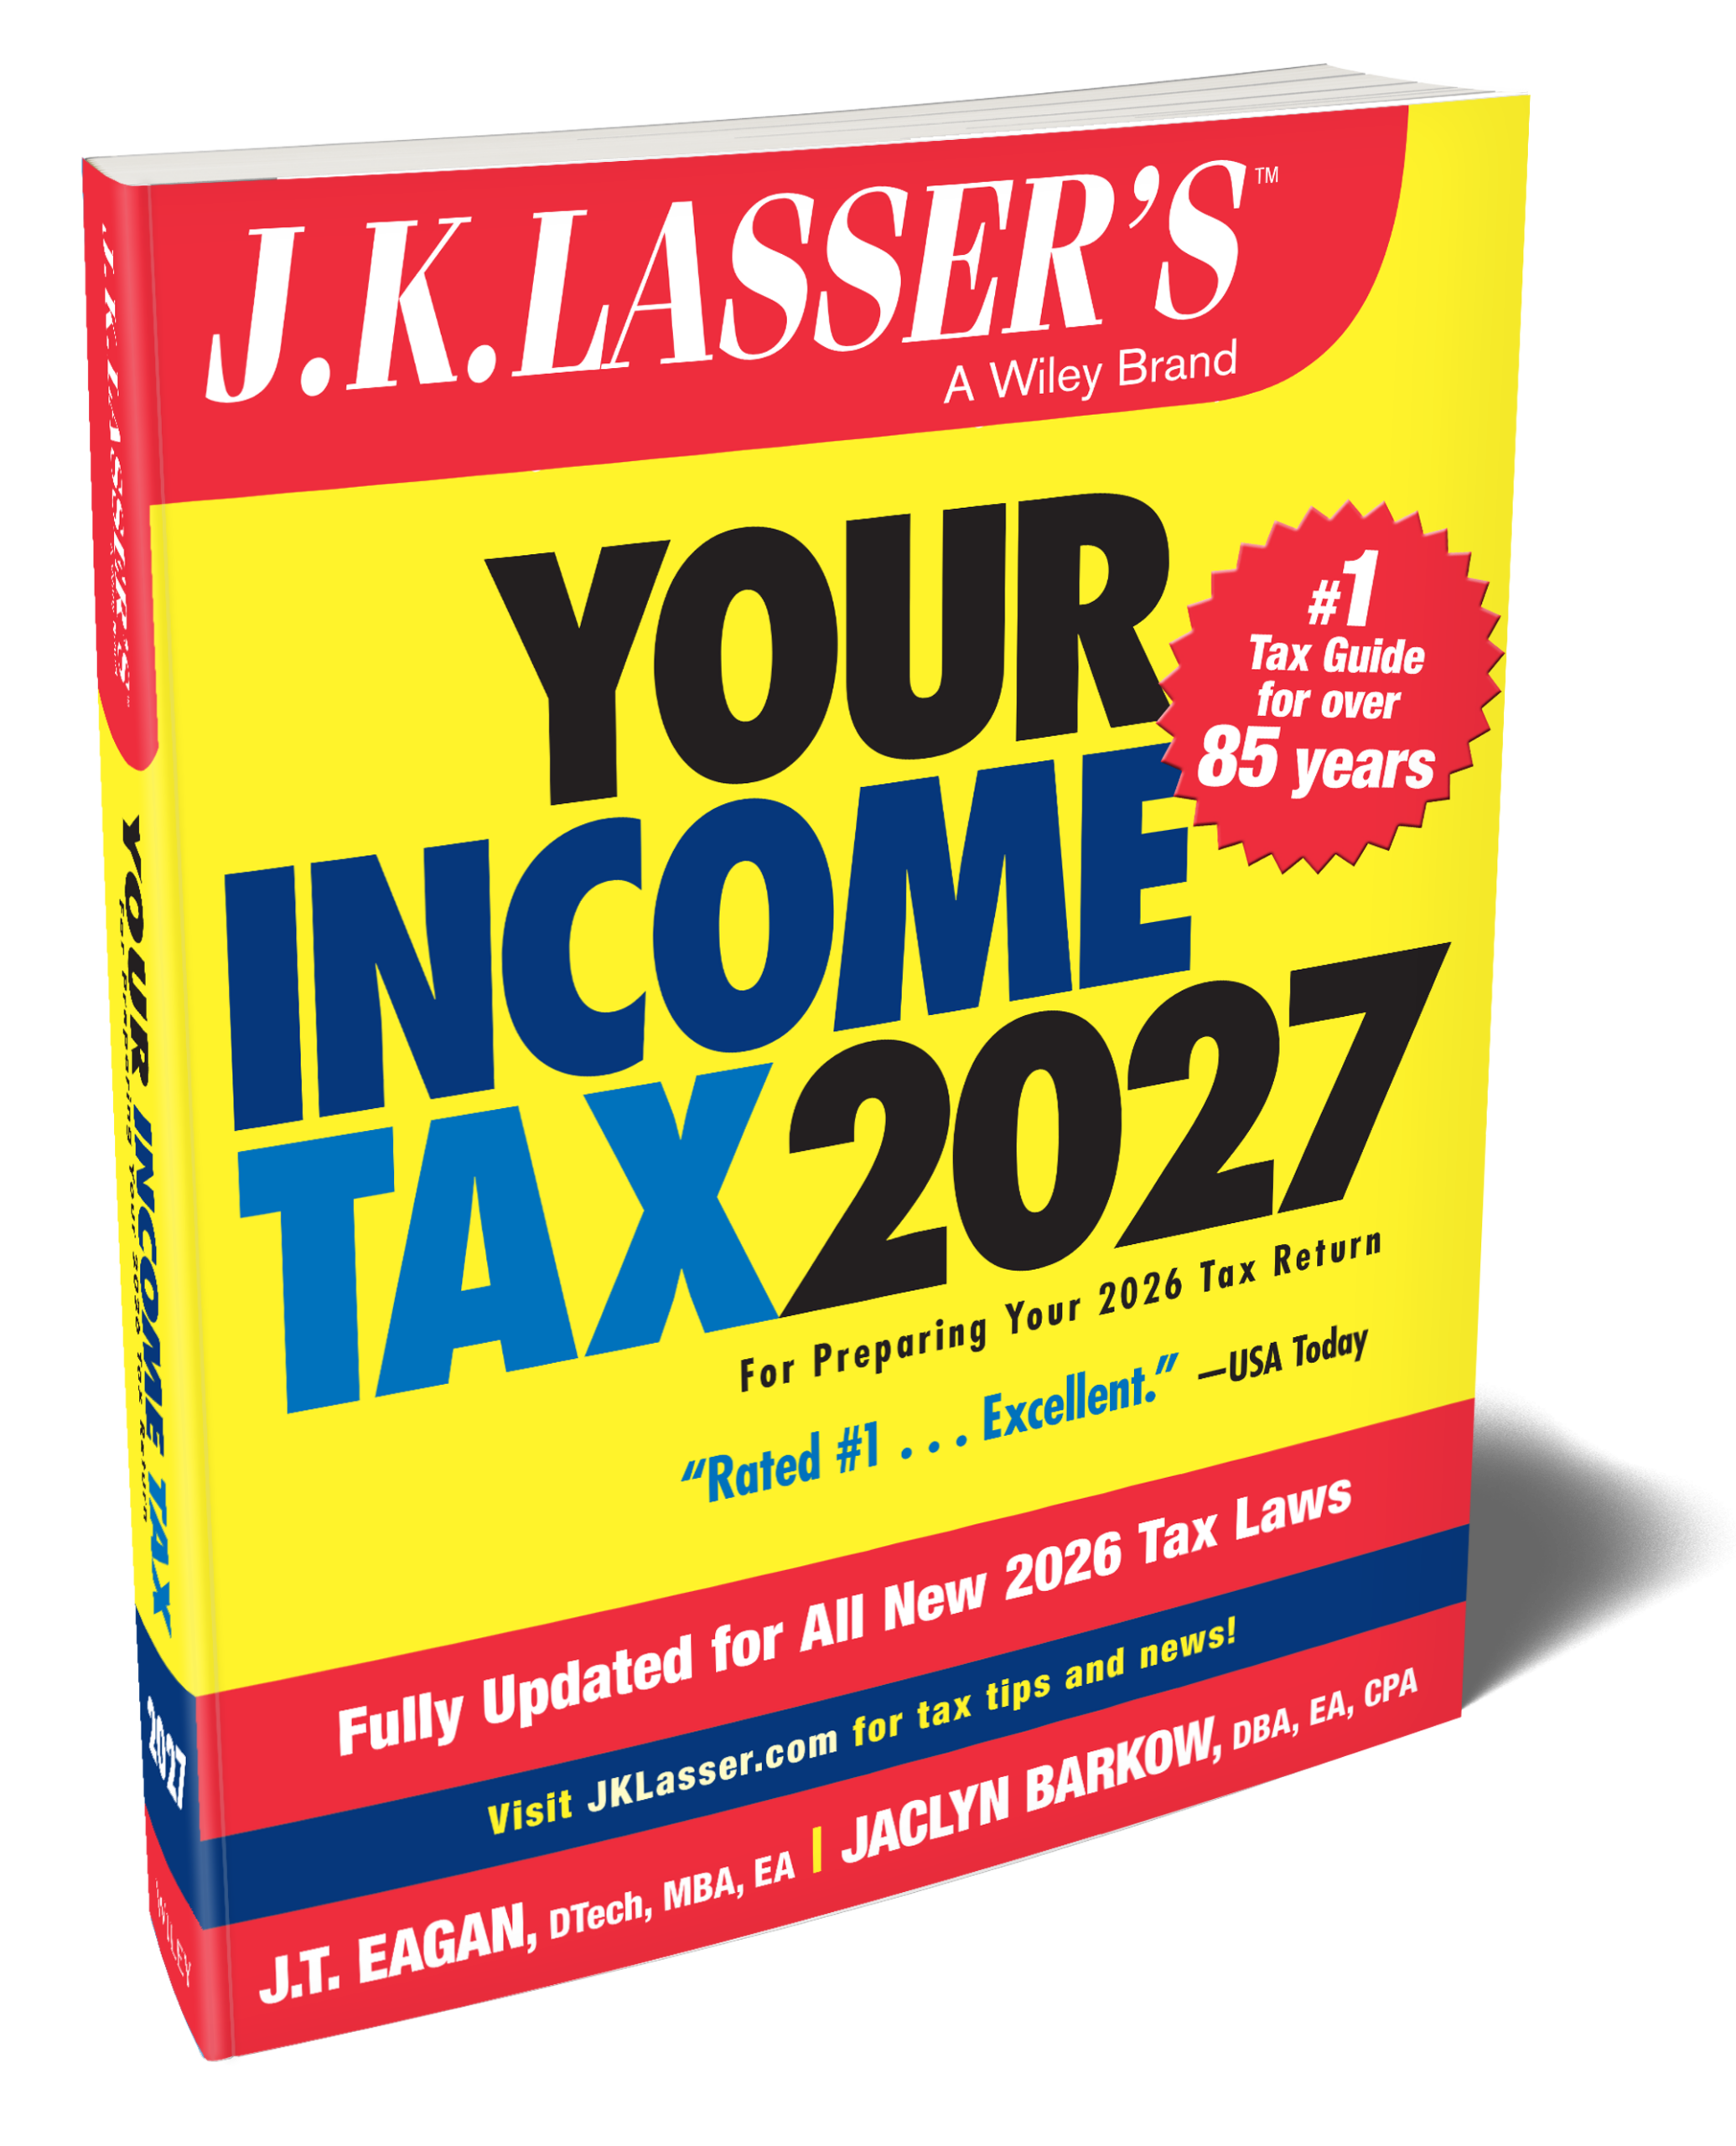
$27.00 
Learn more
To catch up on missed depreciation, you must make a change in accounting method. However, this is an automatic change; you don’t need IRS approval but do have to follow procedures. Details on how to do this can be found in Rev. Proc. 96-31 (https://www.irs.gov/pub/irs-tege/n96-30.pdf).
Return filed by a married person who does not file a joint return. Filing separately may save taxes where each spouse has separate deductions, but certain tax benefits require a joint return.
Copyright © 2000- John Wiley & Sons, Inc., or related companies. All rights reserved. Please read our Privacy Policy.