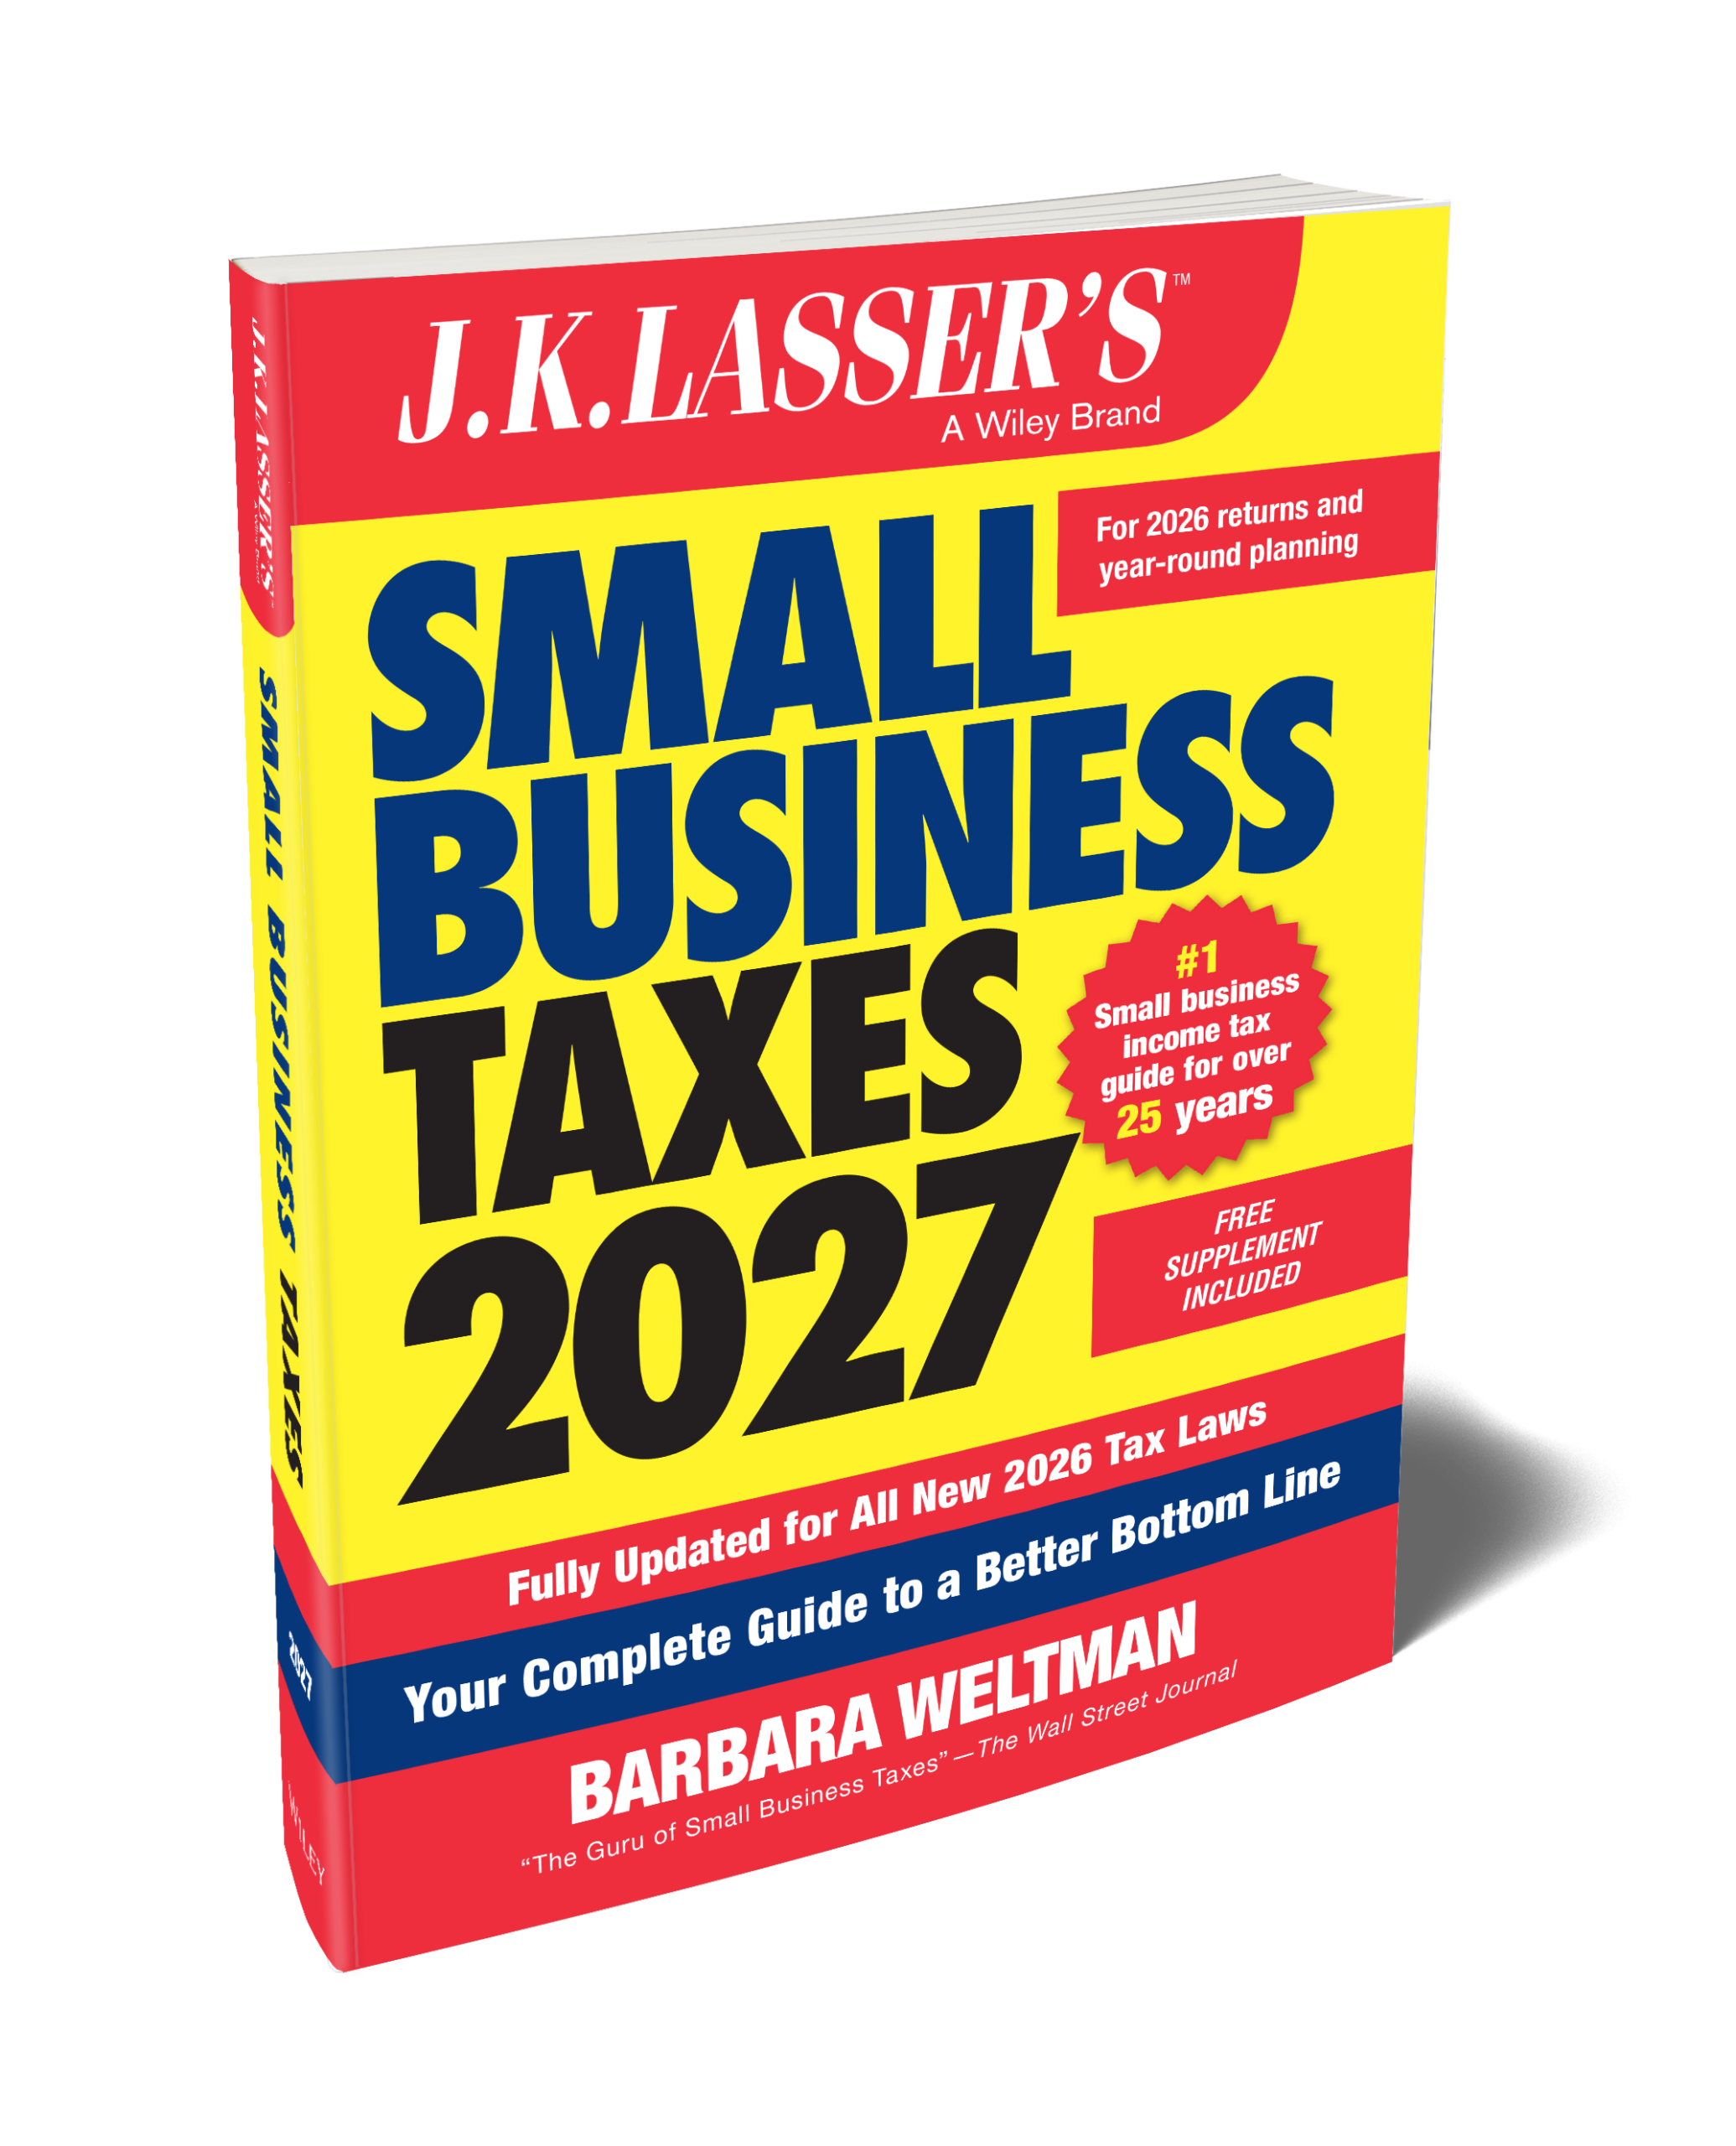
$25.00 
Learn more
For income tax purposes, you cannot take a deduction for this payment and your son is not taxable on it (it’s a gift to him). For gift tax purposes, the first $14,000 is excluded ($28,000 if your spouse consents to split the gift). The excess is a reduction in your lifetime gift tax exemption amount. The lifetime exemption amount is $5 million indexed annually for inflation, making it $5.25 million in 2013.
The difference between amount realized and adjusted basis on the sale or exchange of capital assets. Long-term capital gains are taxed favorably. Capital losses are deducted first against capital gains, and then again up to $3,000 of other income.
Copyright © 2000- John Wiley & Sons, Inc., or related companies. All rights reserved. Please read our Privacy Policy.