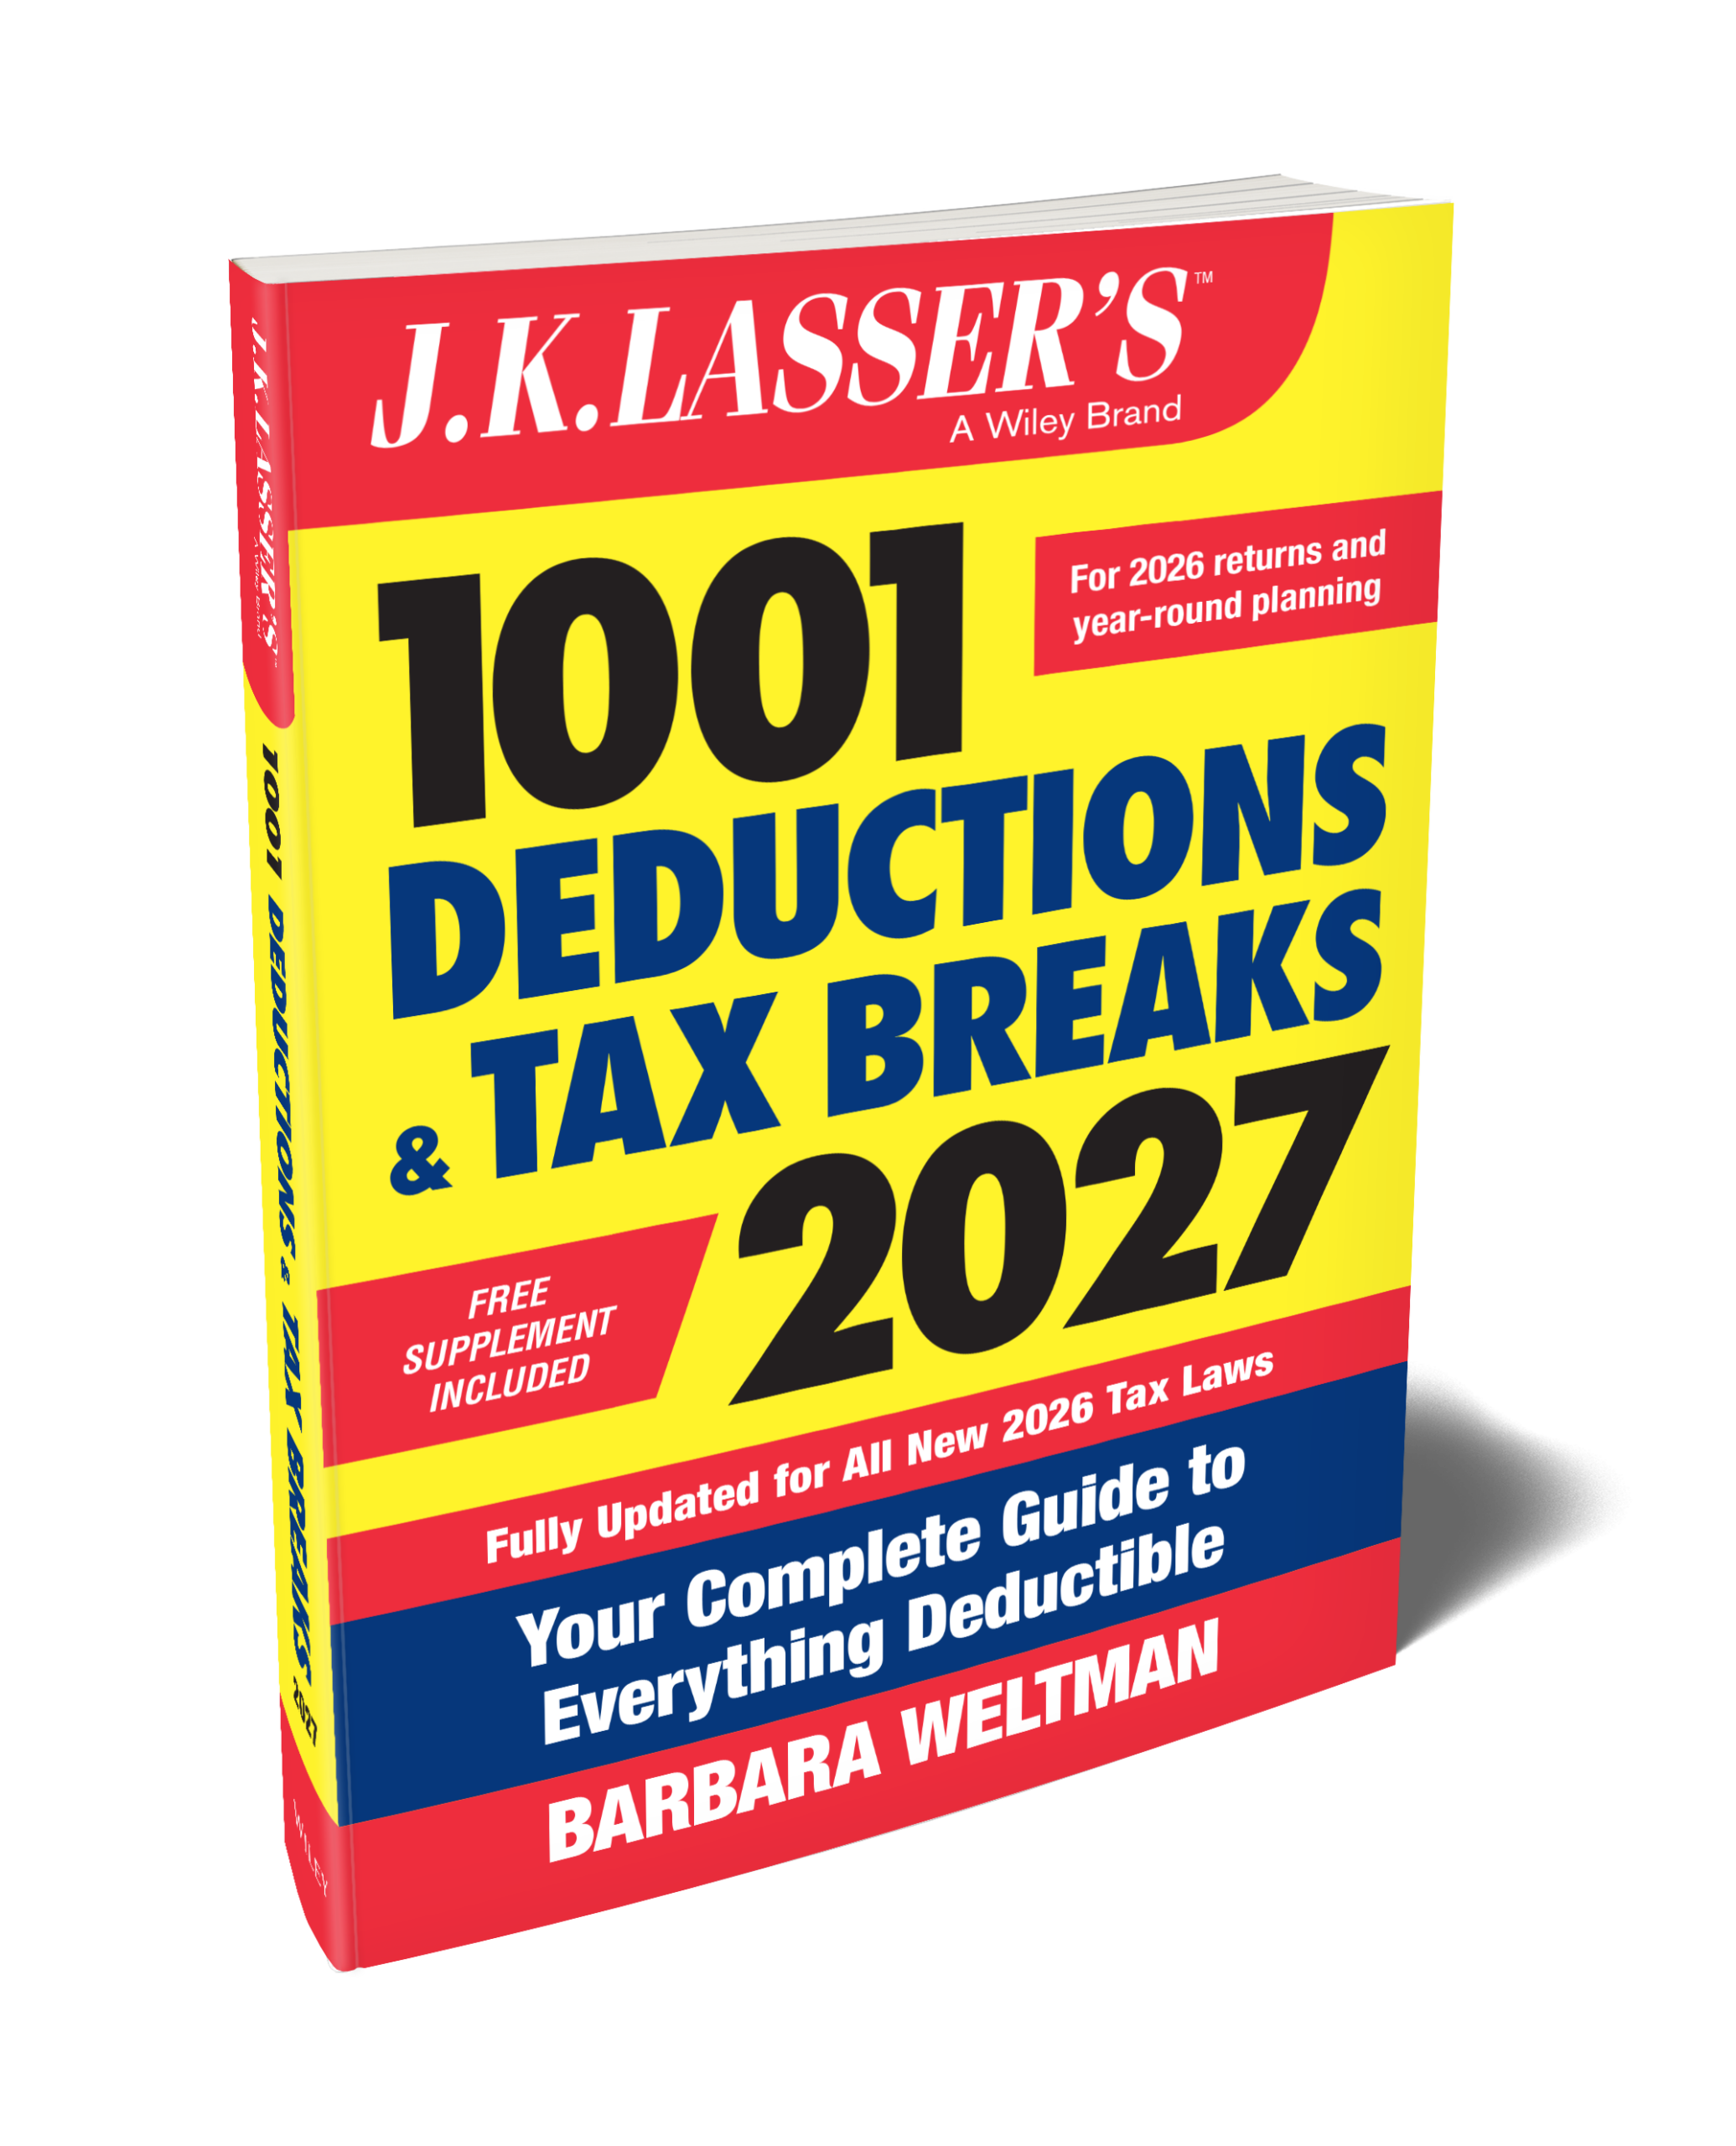
$25.00 
Learn more
When property is transferred from a living (revocable) trust to a beneficiary on the death of the grantor, the beneficiary receives a stepped-up basis. Any appreciation after the grantor’s death is taxable to the beneficiary when he/she sells the property.
An individual who, because of his or her real estate activity, qualifies to deduct rental losses from nonpassive income.
Copyright © 2000- John Wiley & Sons, Inc., or related companies. All rights reserved. Please read our Privacy Policy.