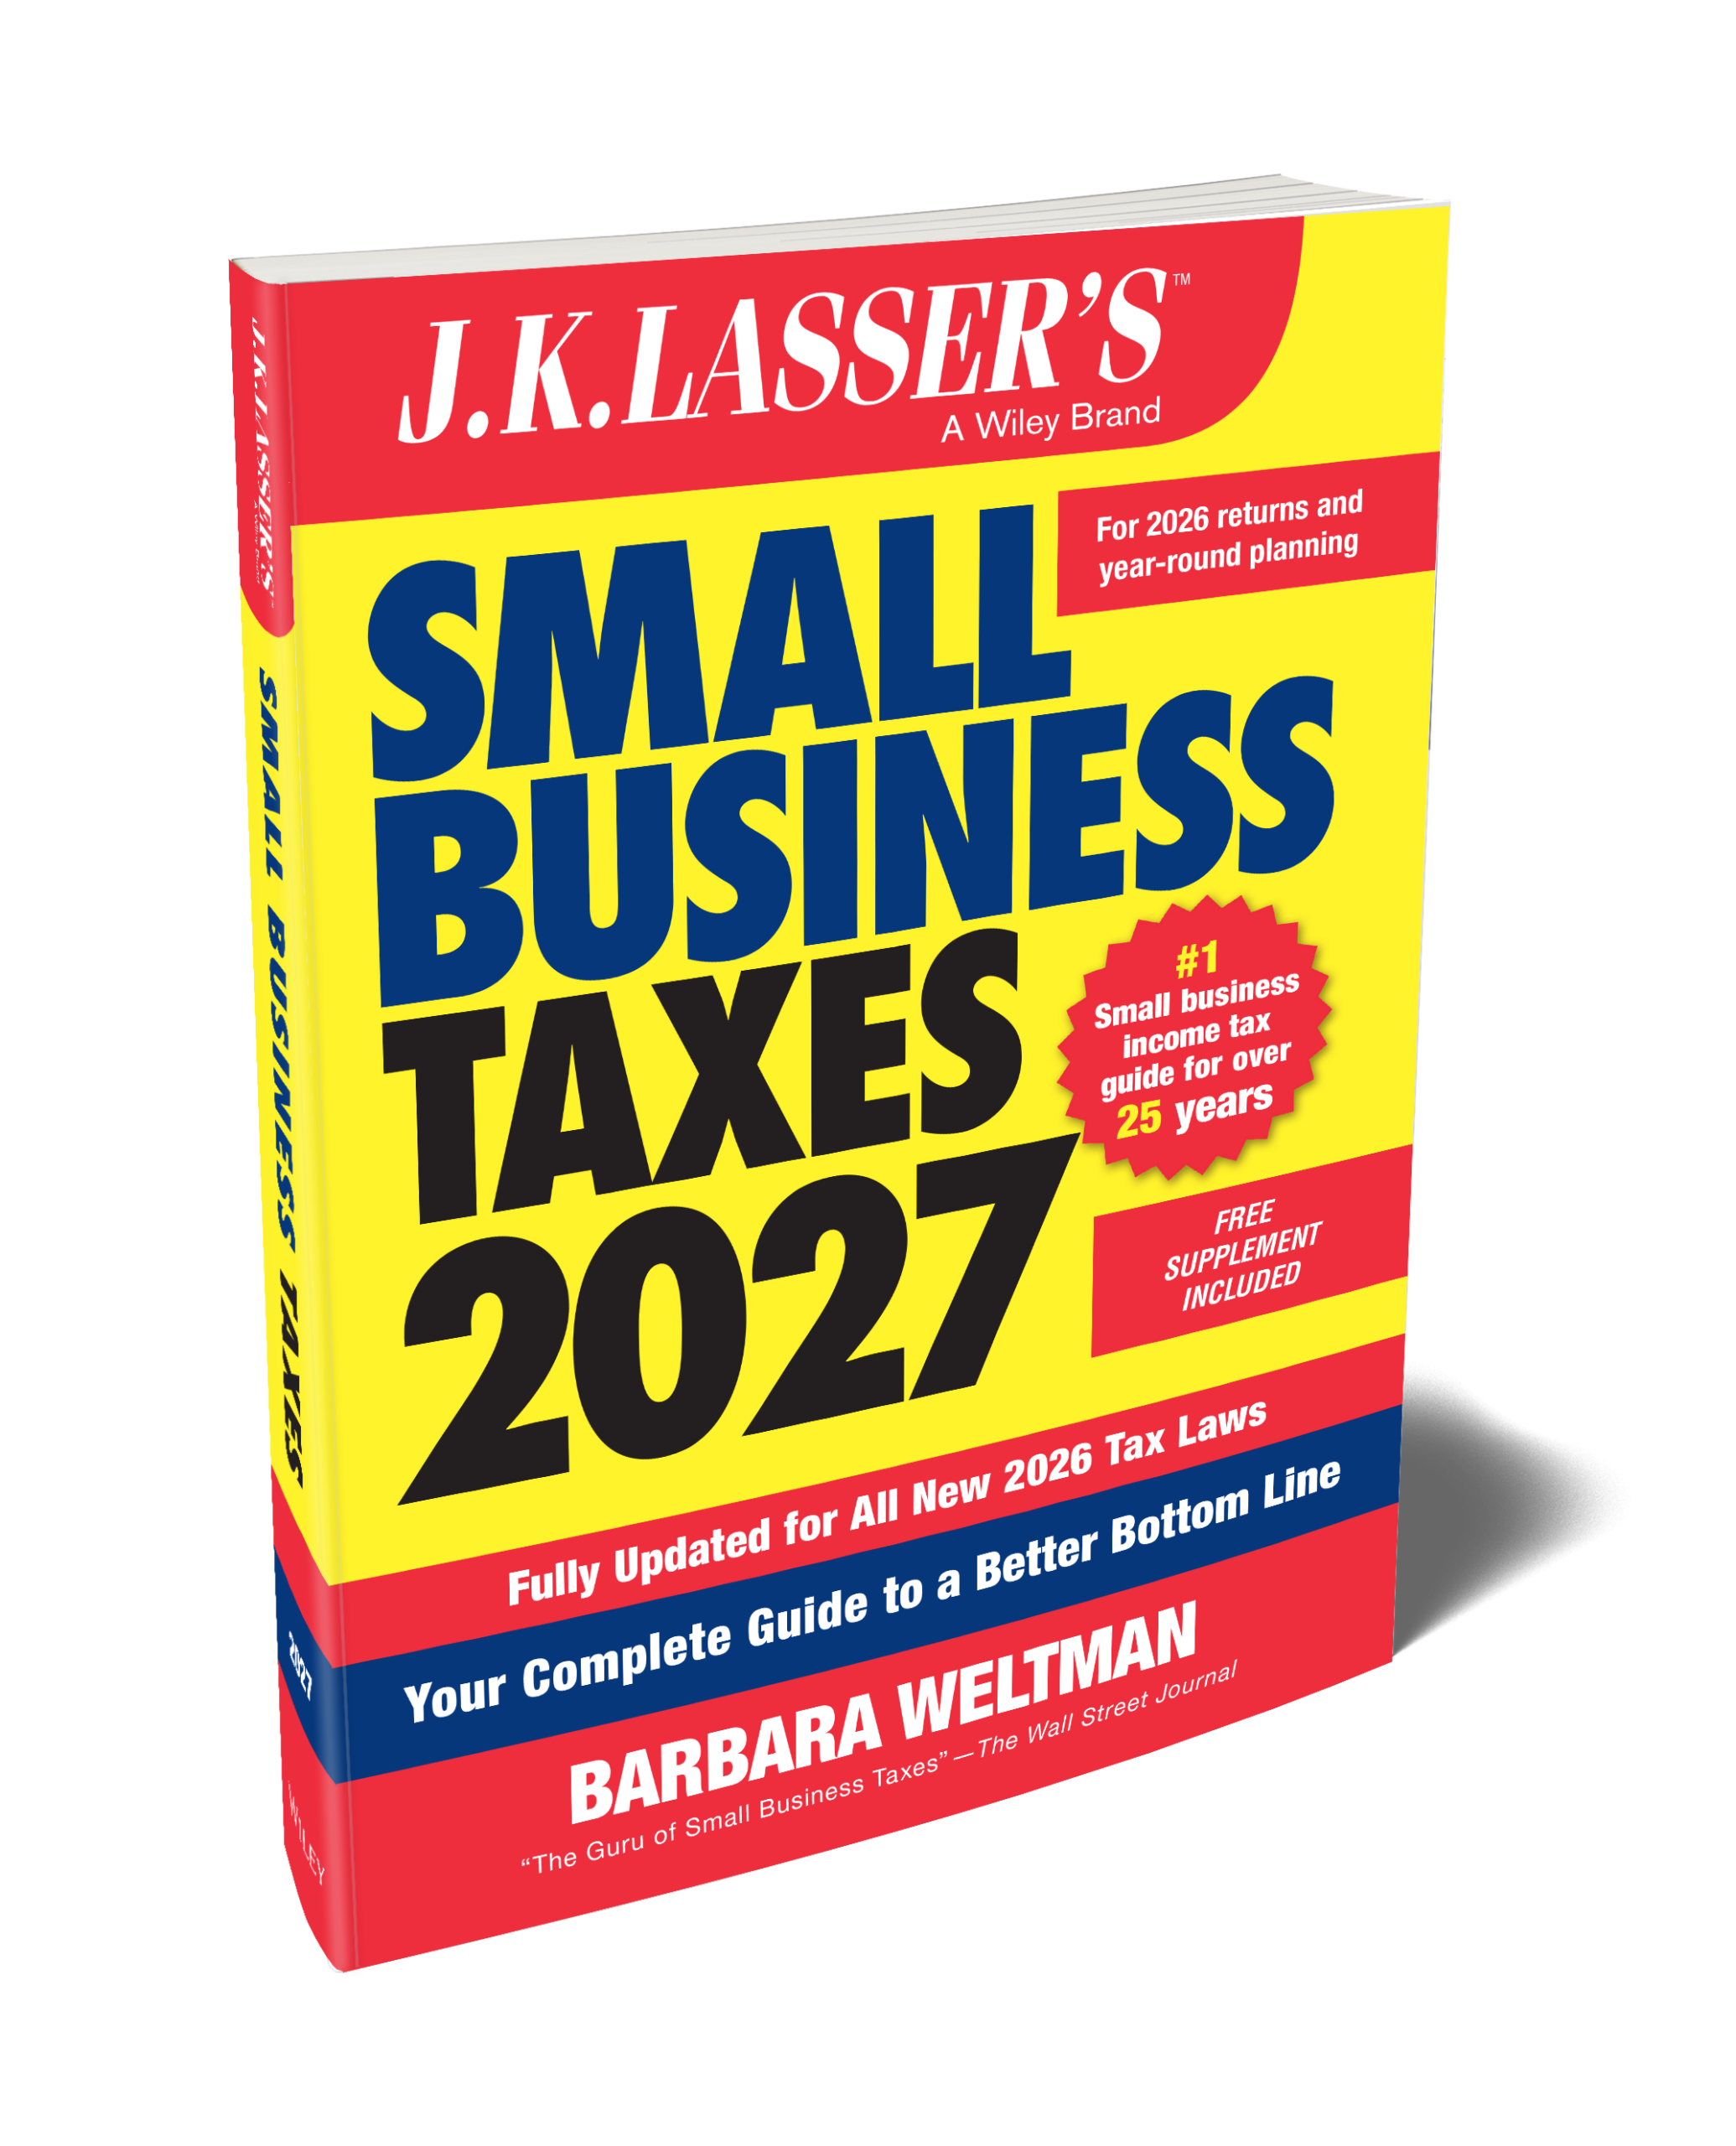
$25.00 
Learn more
If you sell before or after you marry and the sales take place in the year of your wedding, on a joint return you can each use the $250,000 home exclusion. However, if either excludes less than $250,000, the unused exclusion amount cannot be used by the other spouse.
A business loss that exceeds current income may be carried back against income of prior years and carried forward as a deduction from future income until eliminated.
Copyright © 2000- John Wiley & Sons, Inc., or related companies. All rights reserved. Please read our Privacy Policy.