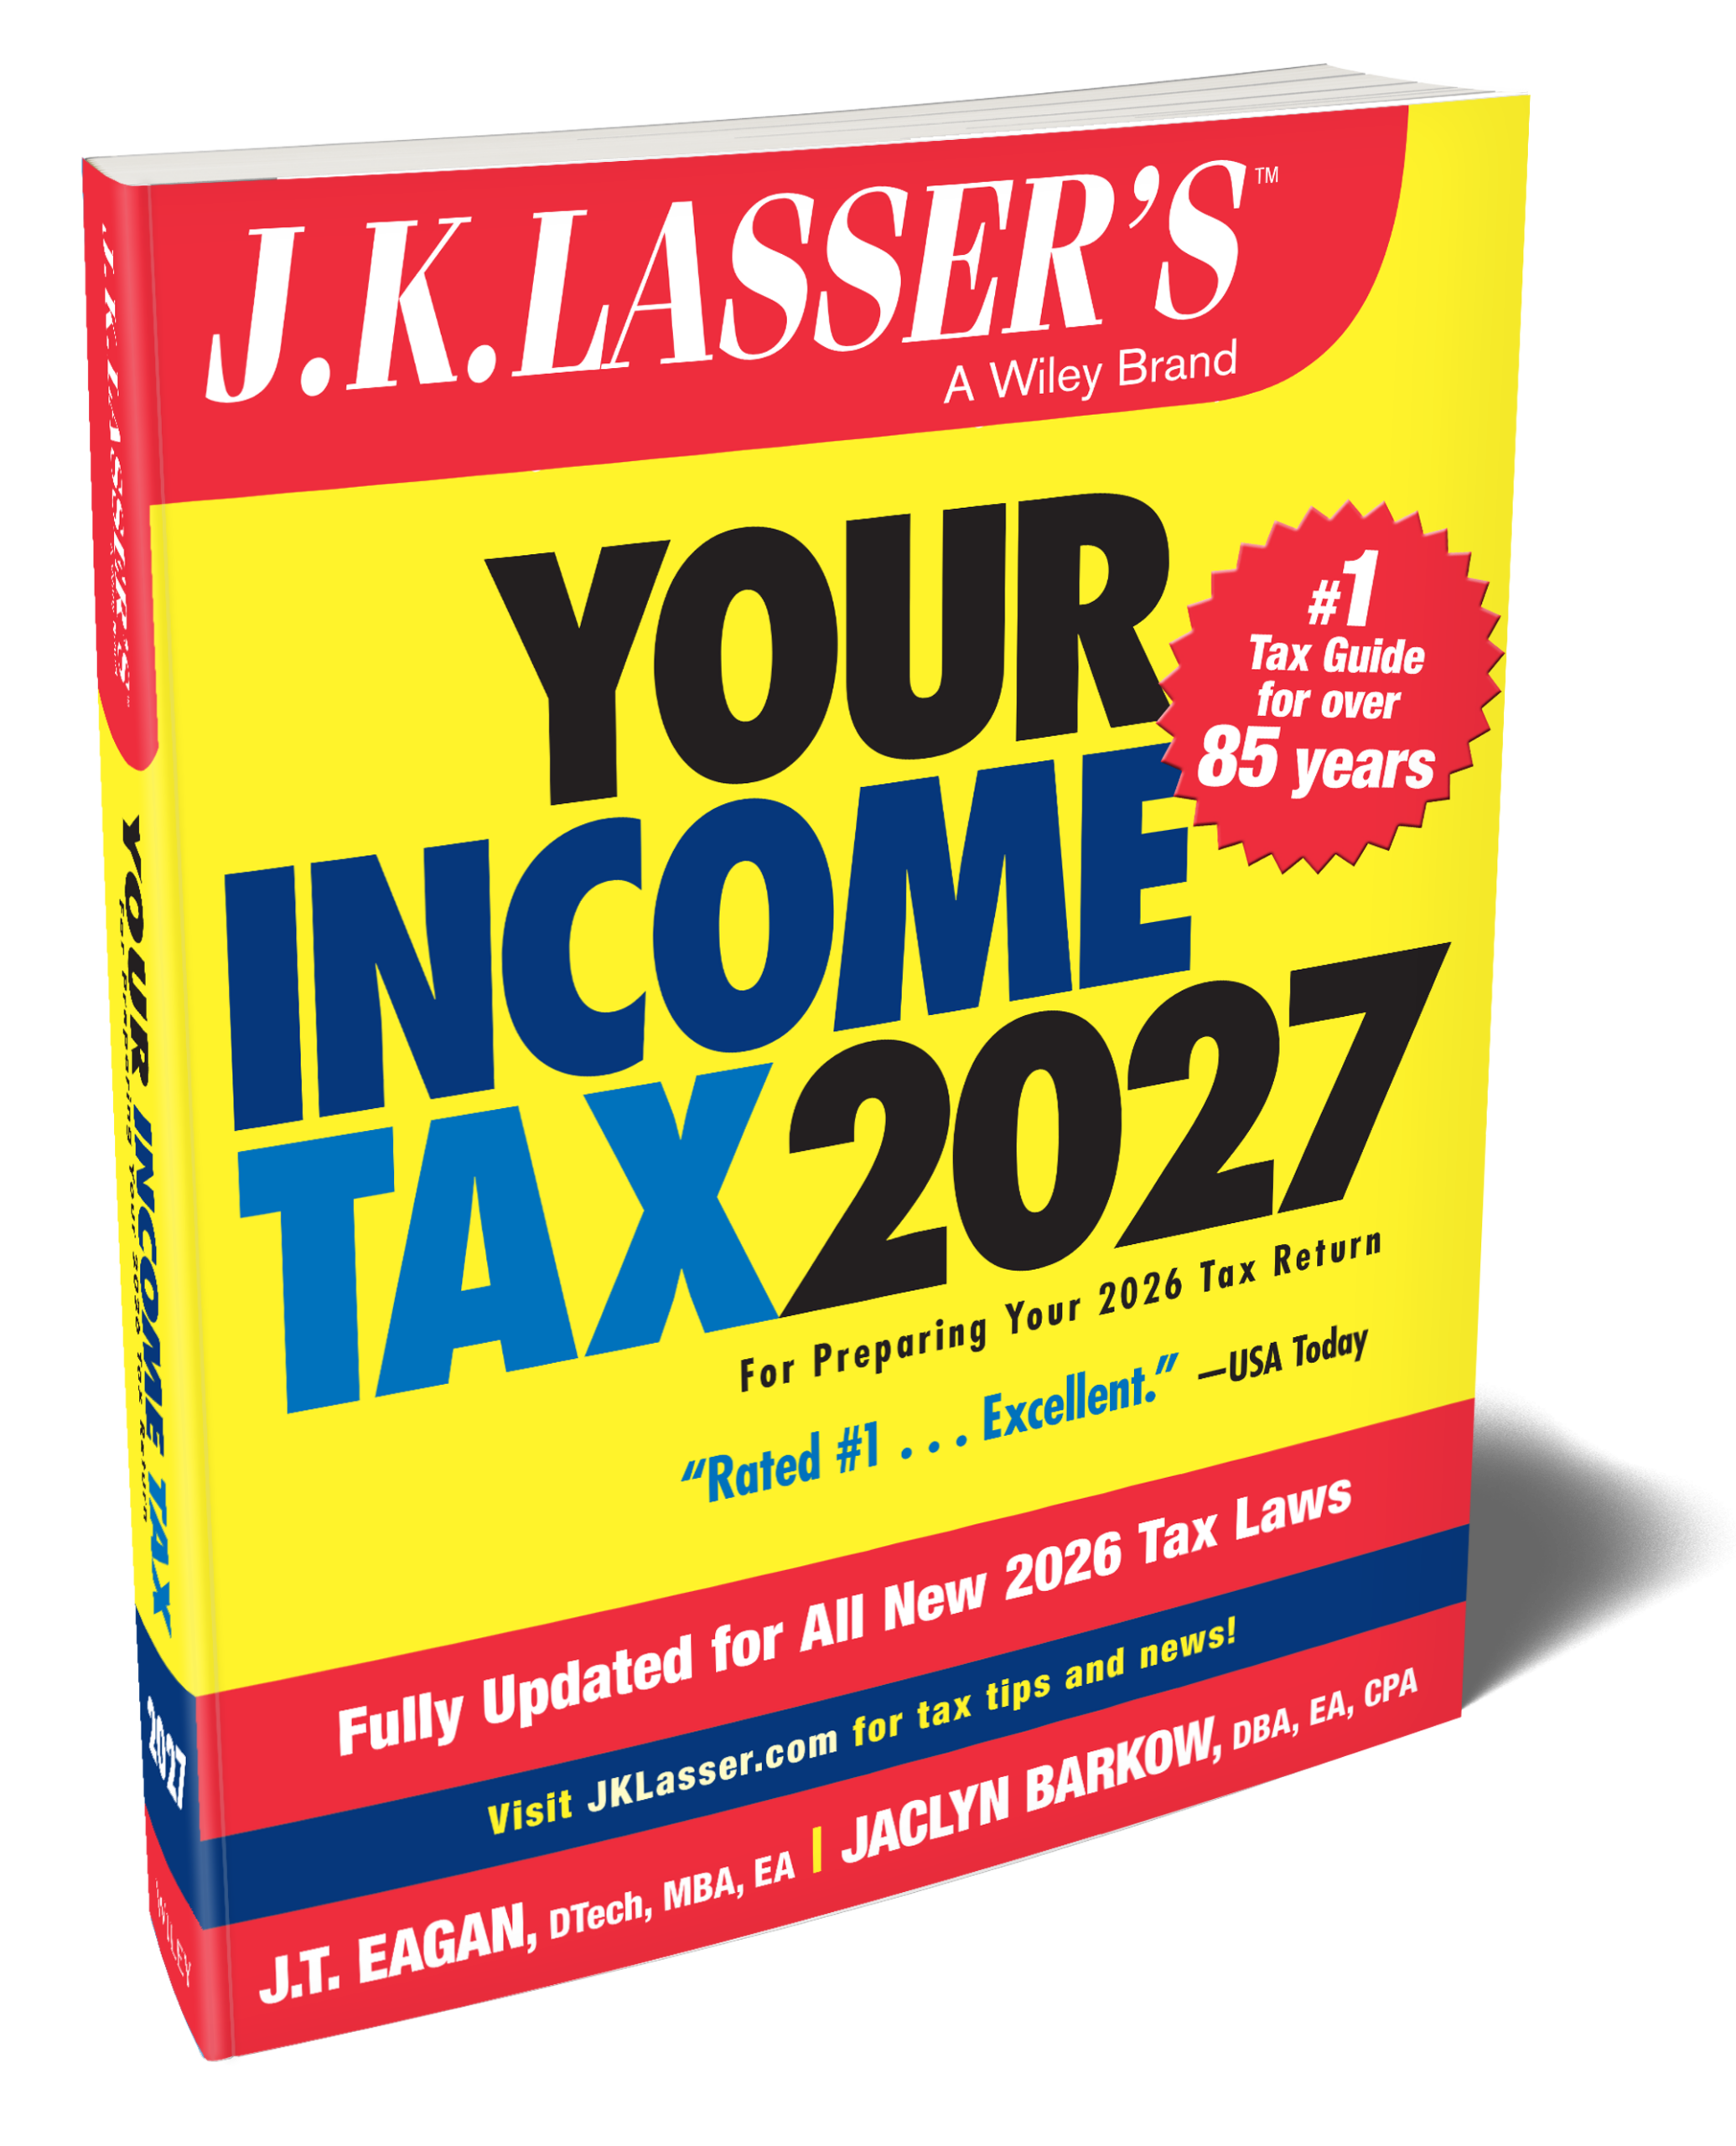
$27.00 
Learn more
Because you are married, you cannot be treated as single. You can file a joint return, or you can opt to file as “married filing separately.” However, if spouses live apart and meet certain tests, one may qualify to file as head of household instead of married filing separately. To do this, you must have a qualifying person live with you (or a dependent parent even if not living with you); a spouse is not a qualifying person.
A credit for income taxes paid to a foreign country or U.S. possession. 401(k) plan. A deferred pay plan, authorized by Section 401(k) of the Internal Revenue Code, under which a percentage of an employee’s salary is withheld and placed in a savings account or the company’s profit-sharing plan. Income accumulates on the deferred amount until withdrawn by the employee at age 59?
Copyright © 2000- John Wiley & Sons, Inc., or related companies. All rights reserved. Please read our Privacy Policy.