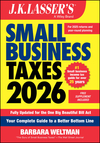
$25.00 
Learn more
The payments are taxable wages to you; effectively, you are an employee of your state.
Gifts in excess of an $12,000-per-donee annual exclusion are subject to gift tax, but the tax may be offset by a gift tax credit.
Copyright © 2000- John Wiley & Sons, Inc., or related companies. All rights reserved. Please read our Privacy Policy.