$27.00 
Learn more
The kickoff to football season is here, and whether you are grinding out daily fantasy lineups, placing parlays on your phone, or trading event contracts, millions of dollars are moving across screens every Sunday.
But before you try to drive down the field, you need to understand the IRS rulebook. You might think a bet is a bet, but the tax code treats traditional sportsbooks, fantasy football leagues, and prediction markets very differently. If you aren’t careful, you could end up taking a massive blindside sack come tax season.
Here is your 2026 tax playbook for football season.
If you place your bets on a standard, app-based sportsbook, your winnings are taxed as ordinary gambling income. But the real story is on the defensive side of the ball: how you write off your losses.
Historically, if you itemized your deductions on Schedule A, you could write off your gambling losses up to the total amount of your winnings. However, the One Big Beautiful Bill Act (OBBBA), enacted on July 4, 2025, introduced a massive blitz starting in 2026. You can now only deduct 90 percent of your wagering losses. Because your deduction still cannot exceed your winnings, the deduction is effectively limited to the lesser of 90 percent of your total losses or 100 percent of your winnings.
The Math Breakdown:
Calling an Audible: The Session Method To minimize the impact of artificially inflated gross winnings, smart bettors look to “Session Accounting”. Rooted in tax court precedent and outlined in IRS Notice 2015-21, this allows you to offset losing wagers 100 percent against winning wagers within a specific, continuous “gambling session” (like a Sunday afternoon of betting). The 90 percent limitation only applies to the net loss realized when the session terminates.
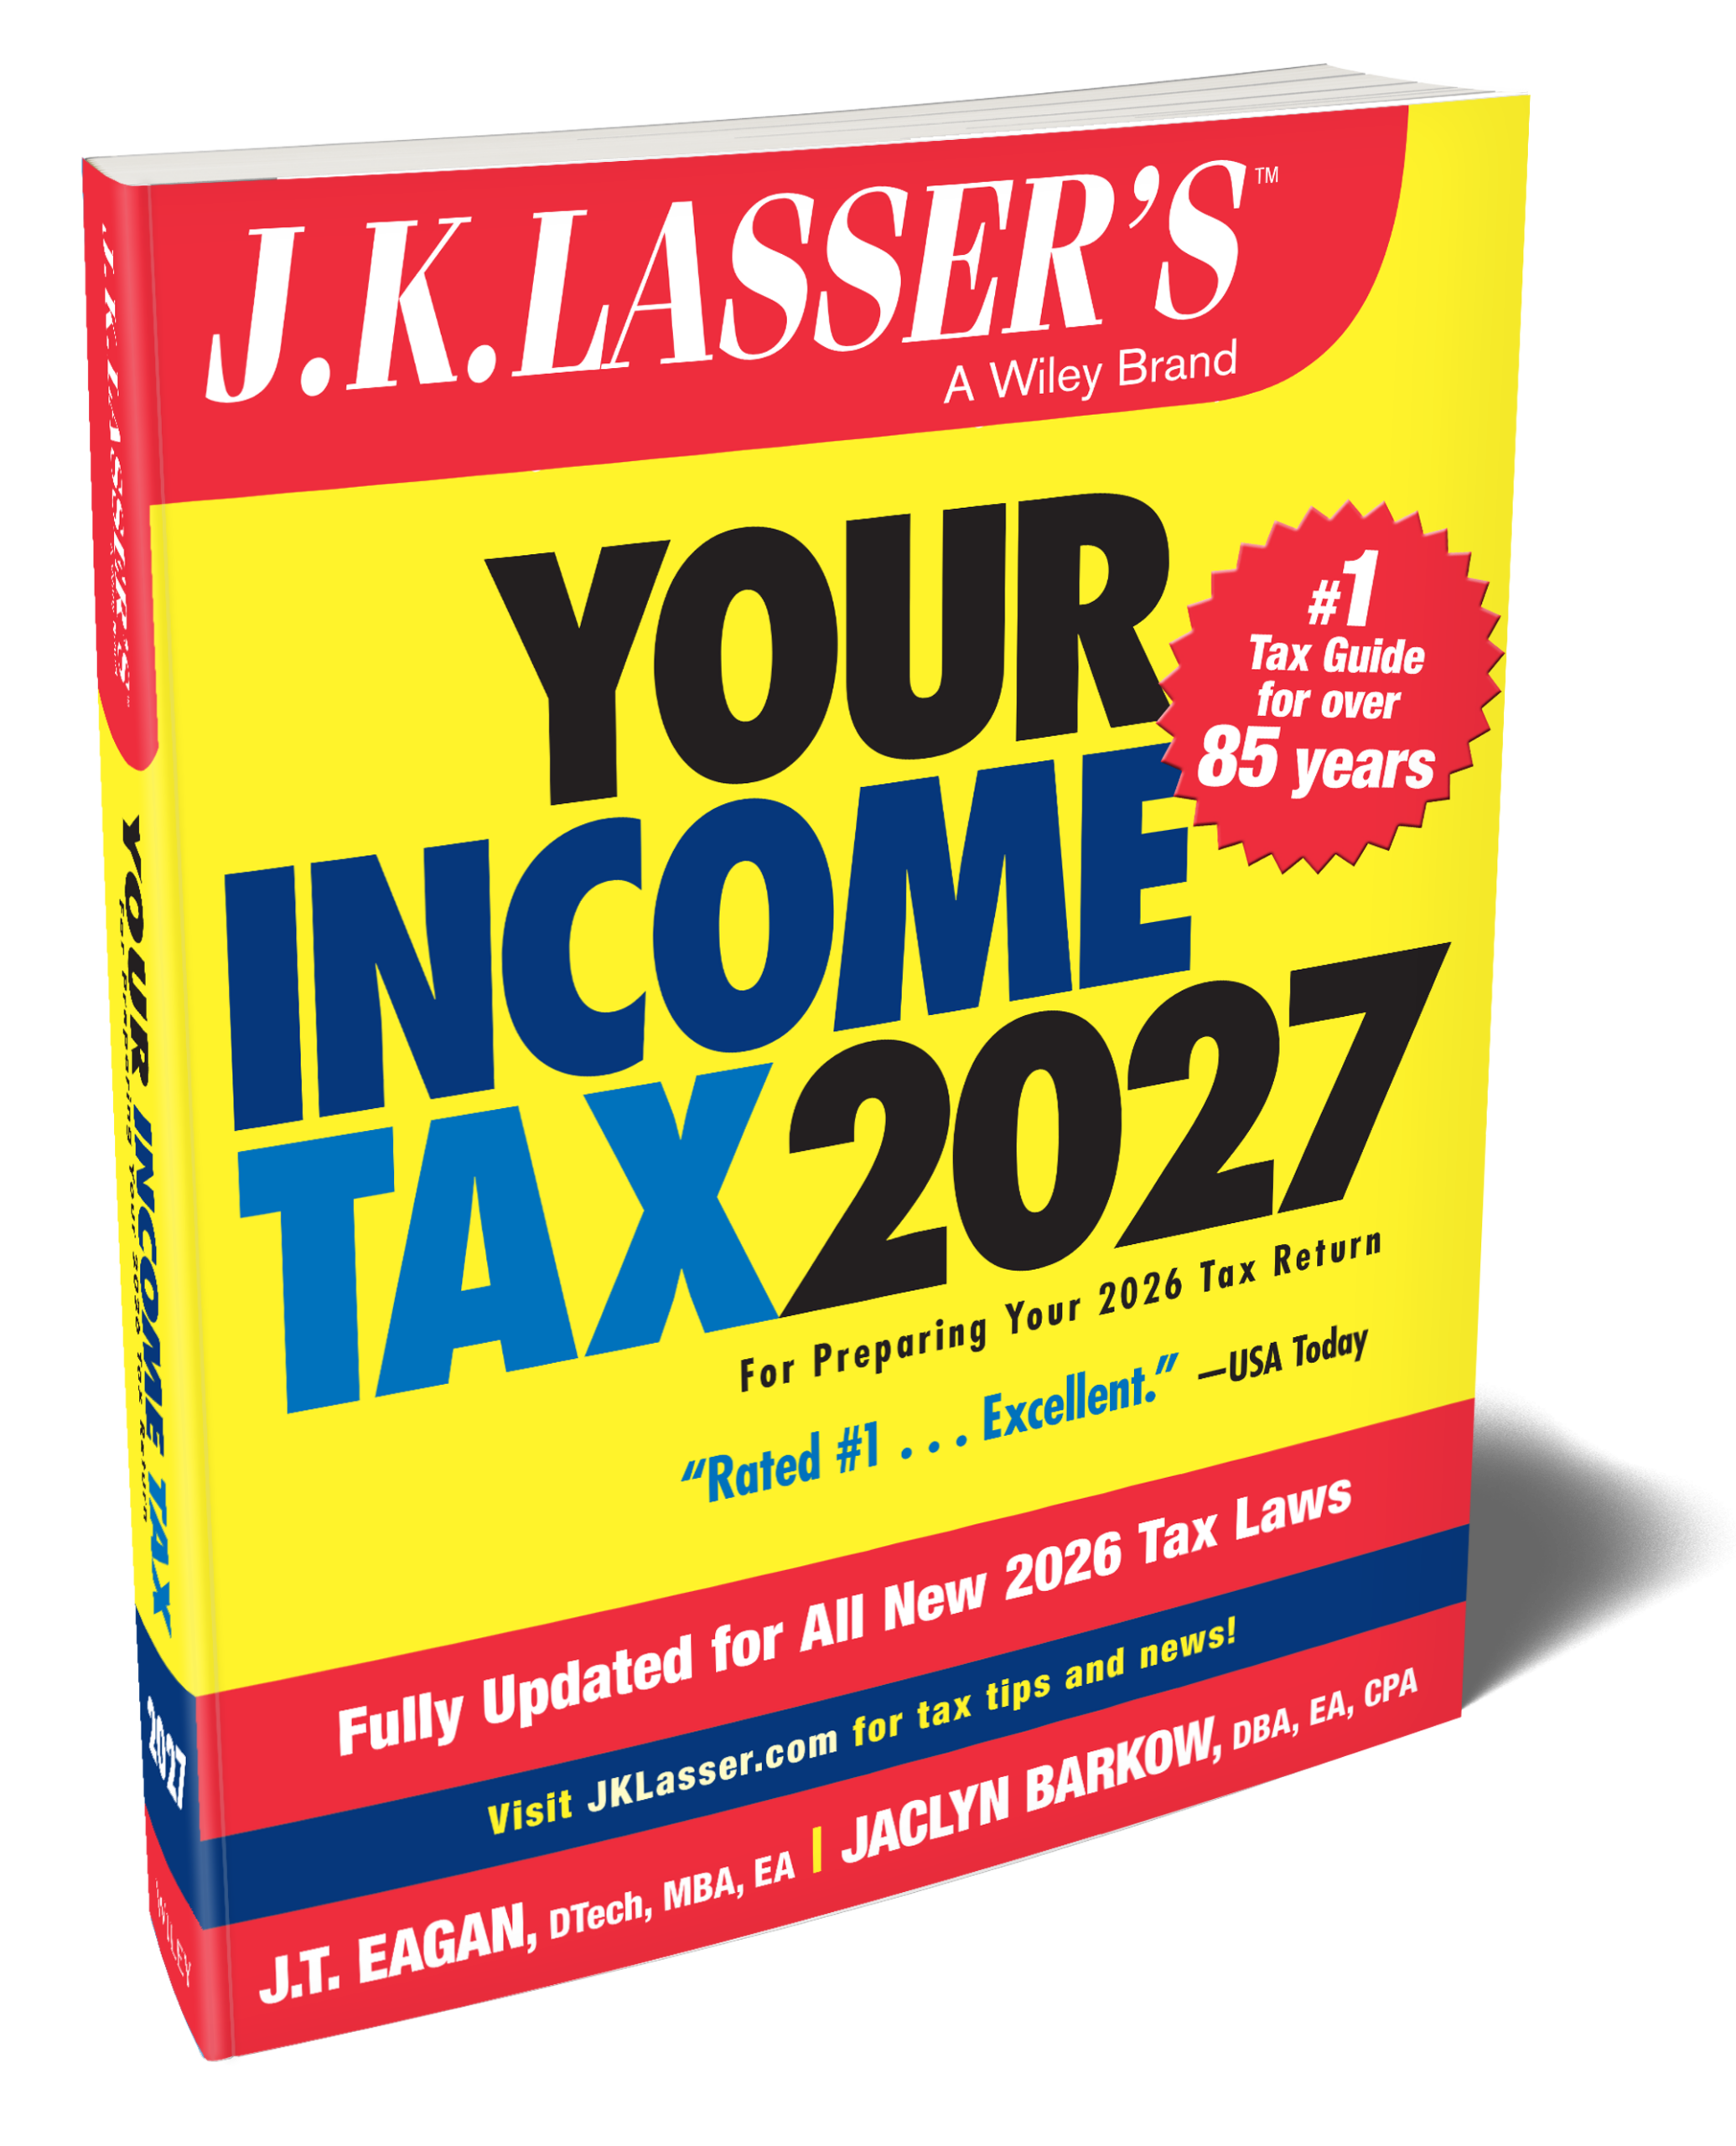
(Note: If you want to know exactly what the IRS considers an acceptable diary for logging your sessions, I highly recommend checking out the Itemized Deductions chapter of J.K. Lasser’s Your Income Tax 2027. It breaks down exactly what you need to track to survive an audit.)
Beware the State Tax Sack: Even if you navigate the federal rules perfectly, check your local jurisdiction. Many states do not allow you to deduct gambling losses at all, meaning you will pay state income tax on your gross winnings regardless of the federal rules.
If you are betting heavily, you might be wondering if you can just call yourself a “professional gambler” and write off your expenses.
To turn pro in the IRS’s eyes, you must face a “fourth and long” criteria test. You must pursue gambling continuously, regularly, and with a legitimate expectation of making a profit. It requires treating betting like a full-time business, complete with rigorous bookkeeping.
If you make the roster, you report your income on Schedule C. This allows you to deduct ordinary and necessary business expenses to lower your net profit. Need an expensive out-of-market Sunday TV package? A premium data analytics subscription? Travel to a casino? Those are now deductible business expenses. (For a full rundown of what you can and cannot write off as a business expense, dive into the Schedule C and Self-Employment section of J.K. Lasser’s Your Income Tax 2027.)
The Catch: The OBBBA 90 percent wagering loss cap still applies to any deduction incurred in carrying on a wagering transaction, which extends to the business expenses of professional gamblers. You can deduct your TV package, but you cannot escape the 90 percent cap on your overall wagering deductions.
Whether you are playing high-stakes Daily Fantasy Sports (DFS) or just a season-long league with your neighbors, the IRS generally treats fantasy sports differently than traditional sportsbooks, often classifying payouts as “Other Income” on Schedule 1.
The League Punishment Penalty
Let’s say you finish dead last in your neighborhood league, and the punishment is that you have to buy a $300 steak dinner for the rest of the league. Can you write that off as a loss against your Week 4 winnings?
Absolutely not. Under IRS rules, a wagering loss requires a stake in a game of chance. Buying dinner for your buddies as a punishment is considered a non-deductible personal expense. Trying to write that off is a massive unforced error. (And don’t forget the “Trophy Tax”—if you win a championship belt or a signed jersey, you owe taxes on its fair market value!)
If you want to avoid the OBBBA limits entirely, you might be looking toward CFTC-regulated prediction markets. The federal government has not definitively stated whether these sports event futures contracts are considered wagering transactions. However, because these platforms operate as regulated financial exchanges, there is a strong argument that betting on an event contract likely qualifies for special “Section 1256” tax treatment.
While the IRS has not yet issued a definitive ruling, if Section 1256 applies, this is the ultimate tax Hail Mary:
(If you are exploring Section 1256 contracts and want to fully understand how the 60/40 capital gains split interacts with your other investments, the Capital Gains and Losses chapter of J.K. Lasser’s Your Income Tax 2027 is the perfect deep dive to help you strategize.)
Disclaimer: Tax laws are complex and change frequently. This article is for informational purposes and does not constitute official legal or tax advice. You may wish to consult a tax professional before finalizing your tax strategy.
A capital loss that is not deductible because it exceeds the annual $3,000 capital loss ceiling. A carryover loss may be deducted from capital gains of later years plus up to $3,000 of ordinary income.
Copyright © 2000- John Wiley & Sons, Inc., or related companies. All rights reserved. Please read our Privacy Policy.